Buying a Flat from an NRI? From 1 October 2026 You No Longer Need a TAN
For thirteen years, a buyer purchasing property from a resident could pay the TDS online in ten minutes using nothing but a PAN — while a buyer purchasing the identical flat from an NRI had to register as a tax deductor first. CBDT Notification No. 121/2026 ends that difference. Here is the new rule: who it covers, the exact rate including surcharge, and the three steps to finish it yourself.
⚡ The New Rule at a Glance
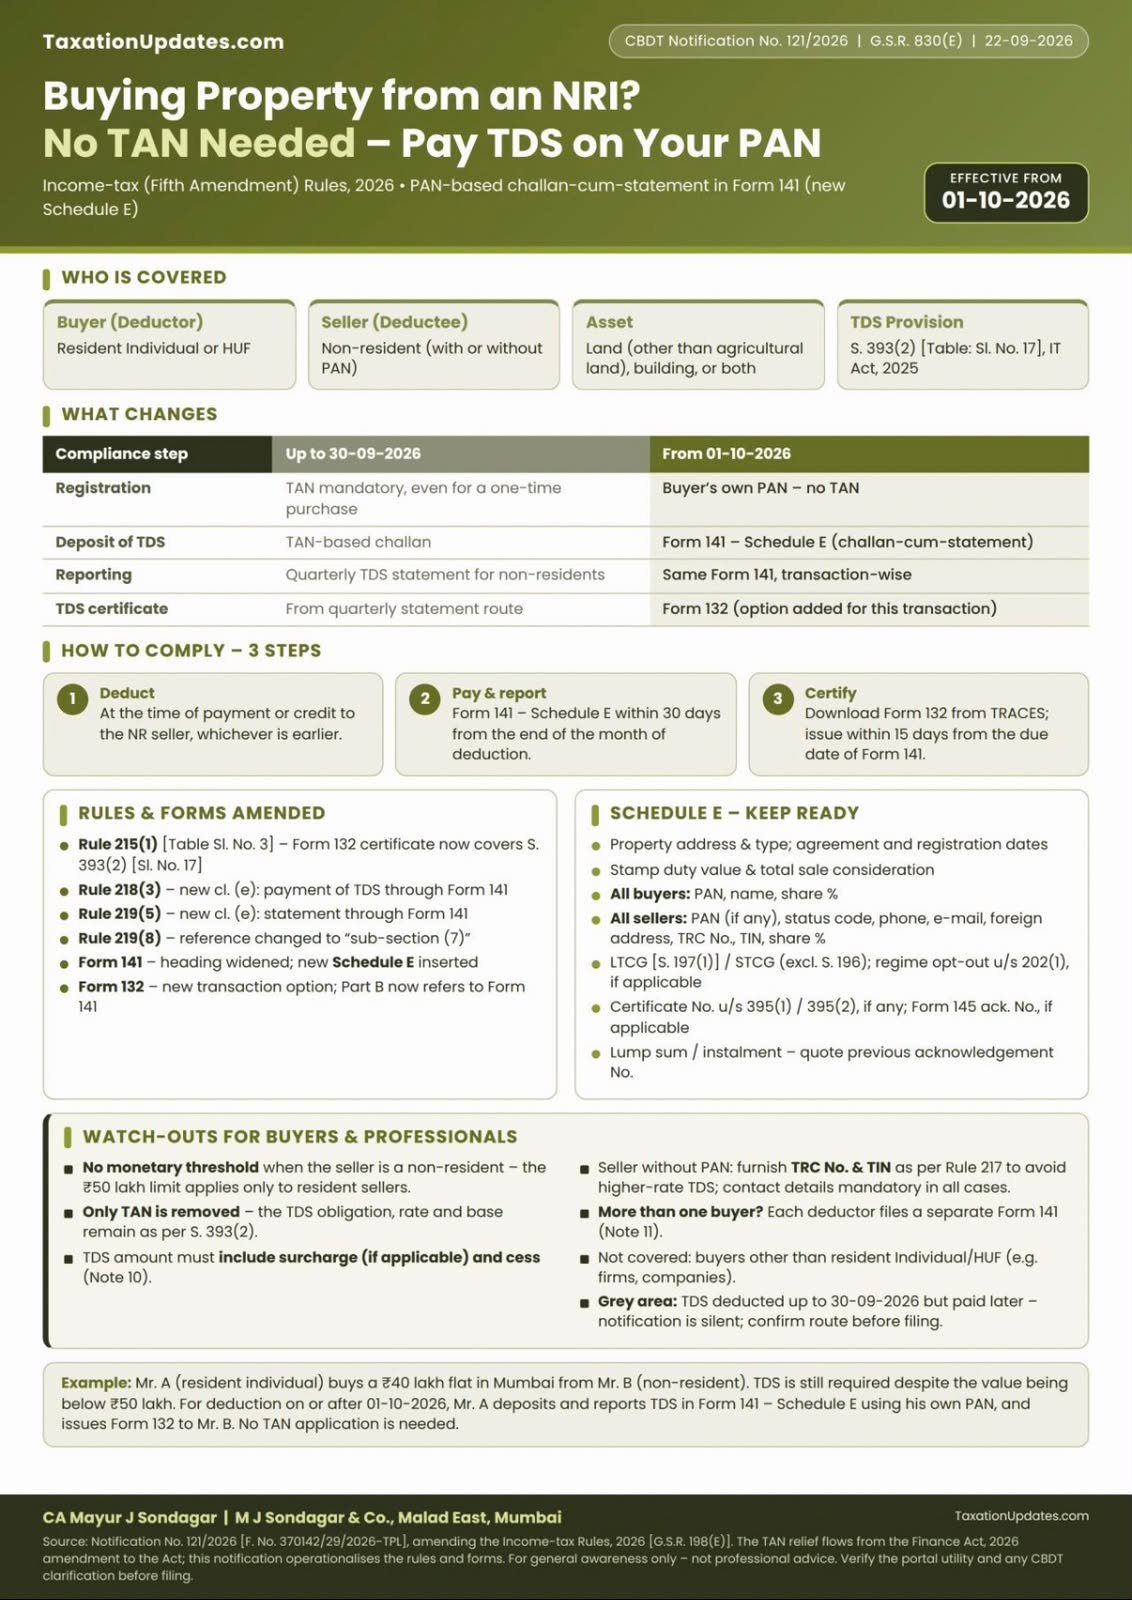
If you are buying a house, a flat, a shop or a plot of land in India and the seller lives abroad, this change is for you. From 1 October 2026, a resident individual or HUF buying immovable property from a non-resident can deduct the tax, deposit it and report it using their own PAN — through a single online form called Form 141, Schedule E. The requirement to first obtain a TAN is gone.
This is one of those rare tax changes that makes life genuinely easier rather than harder. But it does not change how much you must deduct, and that is where buyers still lose money. The rate on an NRI sale is not 1%. There is no ₹50 lakh exemption. And surcharge quietly changes the rate again once the price crosses ₹50 lakh and ₹1 crore. We will take all of it one step at a time.
📌 In one sentence
If you are a resident individual or HUF buying land or a building from a non-resident, then on or after 1 October 2026 you deduct TDS as before, but you now pay and report it on your own PAN in Form 141 – Schedule E within 30 days from the end of the month of deduction, and hand the seller a Form 132 certificate. No TAN. No quarterly TDS return.
The Headache This Rule Removes
To appreciate the relief, you have to understand what buyers were being put through until 30 September 2026.
Most people buy property once or twice in a lifetime. They are not businesses. They do not run a payroll. Yet the moment the seller happened to be an NRI, the law treated the buyer as a professional tax deductor — the same category as a company deducting tax from a thousand salaries every month.
In practice that meant the buyer had to:
- Apply for a TAN — a Tax Deduction and Collection Account Number — in Form 49B, and wait for it to be allotted. A TAN is a separate ten-character number; your PAN cannot be used in its place.
- Deposit the tax using a TAN-based challan, which is a different payment route from the familiar property-TDS page.
- File a quarterly TDS statement for non-residents — a full return, with its own due date and its own late-filing fee of ₹200 per day, even though the buyer had exactly one transaction in their entire life.
- Download the certificate from that quarterly statement and issue it to the seller.
- Keep the TAN alive afterwards. Once allotted, a TAN sits on the department's records. Many buyers simply stopped filing after their one transaction and received default notices years later.
Meanwhile, the buyer of an identical flat from a resident seller logged in with a PAN, filled one page, paid, and downloaded the certificate the same week.
💡 What exactly is a TAN, in plain words?
PAN is your identity number for tax — everyone has one. TAN is a licence to deduct someone else's tax and pay it to the Government on their behalf. It was designed for employers, banks and businesses that deduct tax regularly. Asking a retired couple buying a retirement home to register as a tax deductor was always a mismatch between the law and real life. That mismatch has now been fixed for this one transaction.
The result of the old system was predictable. A very large number of honest buyers either did not know a TAN was needed, or were told by a broker that "property TDS is 1%, just pay it online." They paid 1% on the familiar resident form. Years later came a notice: wrong form, wrong rate, wrong deductor number — with interest from the date of the transaction and the shortfall recoverable from the buyer, not from the seller who had long since taken the money abroad.
A Short History: Why Buying from an NRI Was Always Different
This is not a new tax. The duty to deduct on payments to non-residents is older than the duty to deduct on payments to residents. Here is the whole story in one table.
| When | What happened | What it meant for a property buyer |
|---|---|---|
| 1961 | Section 195 is born | From the very first day of the Income-tax Act, 1961, anyone paying a sum to a non-resident that is chargeable to tax in India had to deduct tax first. There was never a minimum amount. Buying property from a resident, on the other hand, attracted no TDS at all. The asymmetry starts here. |
| 1999 | Supreme Court — Transmission Corporation of A.P. | The Court held that the deductor must deduct on the whole sum paid, not on his own estimate of the seller's profit — unless the tax officer has issued a certificate saying otherwise. This is why, to this day, TDS on an NRI sale is computed on the full sale price and not on the capital gain. |
| 2010 | Supreme Court — GE India Technology Centre | The balancing judgment: there is no obligation to deduct unless the sum is actually chargeable to tax in India. Together, the two judgments produced today's practical rule — deduct on the gross amount, but get a certificate if the real tax is lower. |
| June 2013 | Section 194-IA and Form 26QB | Parliament brings property purchases from residents into TDS: 1% where the price is ₹50 lakh or more. Crucially, it is made PAN-based with no TAN, precisely because ordinary home buyers were the deductors. Non-resident sellers were deliberately left outside this easy route and stayed under Section 195 with full TAN compliance. The gap that Notification 121/2026 now closes was created on this day. |
| 2016 – 2021 | Form 13 goes online | The application for a lower or nil deduction certificate moves to the TRACES portal. An NRI seller can now apply electronically to have the TDS fixed at the real tax on the gain instead of a flat percentage of the whole price. Under the Income-tax Act, 2025 this application is made in Form 128 under Section 395(1), which has replaced the old Form 13 and Section 197. It remains the single most effective way to avoid locking up money. |
| FY 2022-23 | Surcharge on capital gains capped | Surcharge on long-term capital gains is capped at 15%, however large the amount. Before this, high-value sales could attract 25% or 37% surcharge. This cap is the reason the effective TDS rate on a ₹2 crore sale and a ₹20 crore sale is the same today. |
| 23 July 2024 | LTCG rate cut to 12.5% | Long-term capital gains on property move from 20% with indexation to a flat 12.5% without indexation. Resident individuals and HUFs were given a choice between the old and new method for property bought before this date; non-residents were not given that choice. 12.5% is therefore the base rate you start from on an NRI sale. |
| 1 April 2026 | The Income-tax Act, 2025 replaces the 1961 Act | Familiar section numbers change. Section 194-IA becomes Section 393(1) [Table, Sl. No. 3(i)]; Section 195 becomes Section 393(2) [Table, Sl. No. 17]; and Section 197 becomes Section 395, with Form 13 replaced by Form 128. Forms 26QB, 26QC, 26QD and 26QE merge into a single Form 141 with Schedules A to D, and Forms 16B, 16C, 16D and 16E merge into a single certificate, Form 132. |
| 22 Sep 2026 | Notification No. 121/2026 — Schedule E | CBDT inserts a new Schedule E into Form 141 for TDS under Section 393(2) on the purchase of property from a non-resident, and adds the matching option to Form 132. Thirteen years after resident sellers got the easy PAN route, NRI transactions join the same system. Effective 1 October 2026. |
🔎 Read the history this way
In 2013 the Government built a simple, PAN-based conveyor belt for property TDS and put only resident sellers on it. Over the next decade it widened that belt to rent (26QC), to contractor payments (26QD) and to virtual digital assets (26QE), and in 2026 merged all of them into one form with Schedules A to D. Notification 121/2026 simply adds the last missing passenger — the non-resident seller — as Schedule E. Nothing about the tax itself has changed; only the plumbing.
Exactly What Changed on 1 October 2026
Four compliance steps changed. The tax itself did not.
| Compliance step | Up to 30 September 2026 | From 1 October 2026 |
|---|---|---|
| Registration | TAN compulsory, even for a once-in-a-lifetime purchase | Buyer's own PAN — no TAN New |
| Depositing the TDS | TAN-based challan | Form 141 – Schedule E, a challan-cum-statement: the payment and the return are the same form |
| Reporting | Quarterly TDS statement for non-residents | The same Form 141, filed transaction-wise. No quarterly return. |
| Certificate to the seller | Generated from the quarterly statement | Form 132, downloaded from TRACES |
| Rate, base and timing of deduction | Unchanged. Still governed by Section 393(2) — deduct on the full consideration, at the capital-gains rate plus surcharge and cess, at payment or credit, whichever is earlier. | |
✅ What you still have to do
- Deduct at the correct rate, including surcharge and cess
- Deduct on the whole sale consideration, not on the profit
- Deduct at payment or credit, whichever is earlier
- Deposit and report within 30 days from the end of the month
- Issue the certificate to the seller
✕ What is gone for good
- Form 49B TAN application and the wait for allotment
- The separate TAN-based challan
- The quarterly TDS statement for non-residents
- ₹200-a-day late fees on a quarterly return you never knew you had to file
- A dormant TAN sitting on your record for years
📖 For the technically minded: the rules amended
Rule 215(1) [Table, Sl. No. 3] — Form 132 now also covers a deduction under Section 393(2) [Table, Sl. No. 17]. · Rule 218(3) — new clause (e) allows payment of this TDS through Form 141. · Rule 219(5) — new clause (e) allows the statement to be furnished in Form 141. · Rule 219(8) — cross-reference corrected to "sub-section (7)". · Form 141 — heading widened and Schedule E inserted. · Form 132 — new transaction option added; Part B now refers to Form 141.
Note that the relief from TAN itself flows from the amendment made to the Act by the Finance Act, 2026. Notification 121/2026 is the notification that makes the rules and the forms work.
Read the Notification Yourself
Four pages of the Gazette of India. Scroll through it below, or download a copy to keep on the file.
We have summarised it in plain language above, but if you are a professional — or simply the kind of buyer who likes to see the source — here is the notification exactly as published. Page 1 carries the rule amendments, pages 2 to 4 carry the new Schedule E of Form 141 and the Notes that go with it.
The three Notes in Schedule E that matter most
Buried at the end of the notification are the Notes to Form 141. Three of them settle questions that buyers ask us constantly, and they are worth quoting exactly.
| Note | What it says | What it means for you |
|---|---|---|
| Note 10 | Surcharge and cess | “Amount of tax deducted at source shall include surcharge, if applicable, and cess.” — This is the notification itself telling you that deducting a bare 12.5% is not enough. The surcharge and cess are part of the amount you must withhold. |
| Note 11 | Joint buyers | “In case of more than one deductor, each deductor has to file separate form.” — Settles the husband-and-wife question. Two buyers means two Form 141 filings, on two PANs. |
| Note 6 | Seller without a PAN | Contact number, e-mail and the overseas address are mandatory whether or not the non-resident has a PAN. Where there is no PAN, the Tax Residency Certificate number and the Tax Identification Number must be furnished as per rule 217, so that tax is not deducted at the higher rate. |
🔎 Two details in Schedule E worth noticing
Both sides can hold a certificate. Schedule E has two separate fields: “Certificate Number u/s 395(1) of the Act, if obtained by the deductee” and “Certificate Number u/s 395(2) of the Act, if obtained by the deductor”. The seller applies under 395(1); the buyer applies under 395(2). Most commentary mentions only the first.
The word “TAN” does not appear anywhere in this notification. That is not an oversight. The relief from TAN comes from the amendment made to the Act by the Finance Act, 2026; this notification is what makes the rules and the forms actually work. Anyone telling you the notification “abolished TAN” has not read it.
Who Is Covered — and Who Is Not
All four conditions must be satisfied. Miss any one and you are back on the old TAN route.
| Buyer (the deductor) | A resident Individual or HUF |
|---|---|
| Seller (the deductee) | A non-resident — with or without a PAN |
| Asset | Land (other than agricultural land), a building, or both |
| Provision | Section 393(2) [Table, Sl. No. 17] of the Income-tax Act, 2025 |
| Applies to deductions made | On or after 1 October 2026 |
✅ You can use the new PAN route if…
- You are buying in your own name, jointly with family, or in the name of your HUF
- The seller is an NRI, an OCI who is a non-resident, a foreign citizen or any other non-resident
- You are buying a flat, house, shop, office, godown or a non-agricultural plot
- The seller has no PAN — Schedule E has a field for the Tax Residency Certificate and foreign TIN instead
✕ You still need a TAN if…
- The buyer is a company, firm, LLP, AOP, trust or society — only Individuals and HUFs get this relief
- You are buying something that is not land or a building — for example, only the furniture or a business undertaking
- You are making a different kind of payment to the non-resident altogether, such as rent or professional fees
⚠️ First, make sure the seller really is a non-resident
This is the most common factual error in the whole transaction, and it is the buyer who pays for it. Residential status has nothing to do with citizenship, passport, Aadhaar or where the PAN was issued. It depends on the number of days the seller was physically in India in the relevant year and in the preceding years.
A person with an Indian passport and an Indian address can be a non-resident. A foreign citizen living in Mumbai can be a resident. The PAN card does not show status.
Protect yourself: take a written declaration of residential status from the seller in the agreement itself, note the address on the sale deed, and look at the bank account the payment is going to — an NRO or NRE account is a clear signal. If there is any doubt at all, treat the seller as a non-resident and deduct accordingly, or get it confirmed in writing by a professional before you release the money. Read our guide to NRI residential status and taxation for the day-counting rules.
The Rate — and the Surcharge Nobody Tells You About
This section is the one worth reading twice. Getting the rate wrong is what actually costs buyers money.
Step 1 — The base rate
If the NRI has held the property for more than 24 months, the gain is long term and the base rate is 12.5%. If it has been held for 24 months or less, the gain is short term and it is taxed at the slab rates applicable to the seller, which can be considerably higher. Because a buyer has no way of knowing the seller’s other income or slab, the accepted practice on a short-term sale is to deduct at the maximum slab rate of 30%, plus surcharge and cess, and to let the seller recover any excess through a certificate or a return.
Step 2 — The base amount
Here is the point that surprises almost everyone. The 12.5% is applied to the entire sale consideration, not to the seller's profit. You, the buyer, have no way of knowing what the seller paid for the property in 1998, so the law does not ask you to guess — it asks you to deduct on the whole amount and lets the seller sort out the excess later. This has been the position since the Supreme Court's decision in Transmission Corporation of A.P. in 1999.
Step 3 — Add surcharge, then cess
Surcharge is a tax on the tax. It is not a separate percentage of the sale price — it is a percentage of the 12.5%. It kicks in only once the amount crosses ₹50 lakh, and it rises in steps. After the surcharge, a Health and Education Cess of 4% is added on top of the tax-plus-surcharge.
Put together, the effective rate you must actually deduct from the NRI seller looks like this:
| Sale consideration | Surcharge | Cess | Effective TDS on the full sale price |
|---|---|---|---|
| Up to ₹50 lakh | Nil | 4% | 13.00% |
| Above ₹50 lakh up to ₹1 crore | 10% | 4% | 14.30% |
| Above ₹1 crore up to ₹2 crore | 15% | 4% | 14.95% |
| Above ₹2 crore | 15% (capped) | 4% | 14.95% |
+ Surcharge @ 10% = 12.50 × 10% = 1.25% → 13.75%
+ Cess @ 4% = 13.75 × 4% = 0.55% → 14.30%
📐 Three things to note about the surcharge table
- The 15% cap applies to long-term capital gains. This is why a ₹3 crore sale and a ₹30 crore sale both come to 14.95%. For a short-term gain, or where the seller's income is of a different character, the higher surcharge slabs of 25% and 37% can apply and the rate will be materially higher.
- Surcharge and cess are your responsibility as the buyer. If you deduct a clean 12.5% on a ₹1.5 crore flat, you have under-deducted by nearly ₹3.7 lakh. The shortfall, plus interest, is recovered from you.
- Surcharge is strictly reckoned on the seller's income, not on the sale price. Since a buyer cannot know the seller's total income, the settled practice — and the basis of the table above — is to apply the slabs to the consideration being paid. Where the seller obtains a Section 395 certificate, the officer fixes the exact figure and that certificate governs.
- If the seller has no PAN, a higher rate applies — unless the seller furnishes the Tax Residency Certificate, foreign Tax Identification Number and complete contact details. Those contact details are mandatory in every case under the new Schedule E.
💸 The real money-saver: the lower deduction certificate
Deducting roughly 13–15% of the entire sale price is brutal on a seller whose actual gain may be small — someone selling an inherited flat for ₹1 crore might owe tax of ₹2 lakh but see ₹14.95 lakh withheld, recoverable only after filing a return the following year.
The cure exists and is underused. The NRI seller applies online in Form 128 under Section 395(1) for a lower or nil deduction certificate before the sale. The officer computes the real gain and issues a certificate fixing the TDS at the correct, lower figure. Schedule E has a dedicated field for that certificate number. Start it six to eight weeks before the registration date — it is not an overnight process.
You, the buyer, can apply as well. Where part of what you are paying is not chargeable to tax in India at all, Section 395(2) lets the deductor apply to have the taxable portion determined. That is why Schedule E asks for a certificate number under Section 395(1) or 395(2). Note the change of vocabulary: Form 128 has replaced the old Form 13, and Section 395 has replaced Section 197 — an adviser still quoting “Form 13” is working from the 1961 Act.
As the buyer, you must deduct at the full rate unless the certificate is actually in hand on the date of payment. Never accept "the application has been made" as a reason to deduct less. We handle these applications — see our TDS advisory and filing services.
The ₹50 Lakh Confusion — Two Different Rules, Same Number
Almost every buyer has heard "₹50 lakh" in connection with property TDS. The trouble is that ₹50 lakh means two completely different things depending on who the seller is — and the number appearing twice in this article is a coincidence, not a connection.
✕ The myth: "Below ₹50 lakh, no TDS"
This is true only when the seller is a resident. For a resident seller, TDS at 1% applies only if the consideration or the stamp duty value is ₹50 lakh or more. Below that, nothing is deducted.
When the seller is a non-resident, there is no threshold at all. It has never existed under Section 195, and it does not exist under Section 393(2). A ₹40 lakh flat, a ₹15 lakh plot, even a ₹5 lakh garage — TDS applies from the first rupee.
✓ The reality: ₹50 lakh only decides the rate
In an NRI transaction, ₹50 lakh is simply the point at which the surcharge starts. Below it, the effective rate is 13.00%. Above it, 14.30%.
So the ₹50 lakh figure never answers the question "do I deduct?" — the answer to that is always yes. It only answers the question "how much?"
🚨 The single most expensive mistake in this entire article
A buyer purchasing a ₹40 lakh flat from an NRI, told by the broker that "there is no TDS below ₹50 lakh", deducts nothing and pays the seller in full.
The correct deduction was ₹5,20,000 (13% of ₹40 lakh). The seller has taken the full ₹40 lakh abroad. The department recovers the ₹5.20 lakh from the buyer, with interest at 1% per month from the date the tax should have been deducted, plus interest at 1.5% per month from deduction to payment — and the buyer is treated as an assessee in default.
Recovering it from the seller afterwards is a civil matter, not a tax matter. In practice, the money is gone.
How to Comply — Three Steps, One Form, Your Own PAN
This is the part that has become genuinely simple. Read it once and you will see that the whole job is a single sitting at a computer.
Deduct
Hold back the TDS at the time of payment or credit to the NRI seller, whichever is earlier — including on the booking advance and on every instalment, not only on the final payment.
Pay the seller the net amount. Never pay in full and promise to deposit the tax later.
Pay and report
Log in with your own PAN and file Form 141 – Schedule E. It is a challan-cum-statement: the same form pays the tax and reports the transaction.
Within 30 days from the end of the month in which you deducted. Deducted on 12 November? Due by 30 December.
Certify
Download Form 132 from the TRACES portal and give it to the NRI seller. This is their proof of the tax paid, and what they will use to claim credit or a refund.
Within 15 days from the due date of furnishing Form 141.
That is the entire compliance. There is no step four. No TAN application sits in front of step one any more, and no quarterly return sits behind step three.
🗓️ Worked timing example
You register the sale deed and make the final payment to the NRI seller on 18 November 2026.
→ TDS must be deducted on 18 November 2026 (or earlier, if you credited the amount earlier).
→ Form 141 – Schedule E must be filed and the tax paid by 30 December 2026 (30 days from 30 November).
→ Form 132 must be issued to the seller by 14 January 2027 (15 days from the Form 141 due date).
👫 Buying jointly? Each buyer files separately
If a husband and wife buy a flat together, they are two deductors. Each one deducts on their own share of the consideration and files a separate Form 141 using their own PAN. Do not put the whole transaction on one spouse's PAN because it is easier — the shares shown must match the shares in the sale deed, and Schedule E asks for each buyer's PAN, name and share percentage.
The same applies to the seller's side: if an NRI couple sells jointly, each seller's share is reported with their own details.
🏗️ Paying in instalments, as in an under-construction purchase?
Deduct on every instalment as it is paid, and file a Form 141 for each one. Schedule E asks whether the payment is the first, a subsequent or the last instalment, and asks you to quote the acknowledgement number of the previous Form 141. Keep every acknowledgement safely — you will need the last one each time.
Keep This Ready Before You Open Schedule E
Collect all of this from the seller before you release any money. Once the seller is back abroad with the funds, getting a Tax Residency Certificate out of them is very difficult.
🏠 About the property and the deal
- Complete property address and type — land, building, or both
- Date of the agreement and date of registration
- Stamp duty value and the total sale consideration
- Whether this payment is a lump sum, or the first / a subsequent / the last instalment
- For an instalment, the acknowledgement number of the previous Form 141
🧾 About the people
- Every buyer: PAN, name and share percentage
- Every seller: PAN (if any), status code, phone, e-mail and full overseas address
- Tax Residency Certificate number and foreign TIN — mandatory where the seller has no PAN, and advisable in every case
- Contact details are mandatory for all sellers, PAN or no PAN
📊 About the tax
- Whether the gain is long term or short term
- The TDS rate applied, and the surcharge and cess included in it
- Number of the lower or nil deduction certificate under Section 395, if the seller has one
- Whether the seller has opted out of the default tax regime
- Acknowledgement number of Form 145, where applicable
💡 Practical tip
Build these into the sale agreement itself as a seller's obligation, with a clause that the balance payment is released only once the documents are handed over. A seller who knows from day one that a TRC and TIN are required will arrange them. A seller asked for them a week after receiving the money will not.
Also agree in writing who bears the TDS and at what rate, so that the figure does not become a dispute at the sub-registrar's office on registration day.
Mistakes That Cost Buyers Real Money
Every one of these is something we have seen go wrong. The common thread: in each case the buyer ends up paying, not the seller.
| The mistake | Why it happens | What it costs you |
|---|---|---|
| Deducting 1% out of habit | 1% is the rate everyone knows, and the broker or even the society office repeats it. It is the rate for a resident seller. | On a ₹1 crore flat you deduct ₹1 lakh instead of ₹14.30 lakh. A shortfall of ₹13.30 lakh, plus interest, recovered from you. |
| Assuming the ₹50 lakh exemption applies | The threshold genuinely exists — but only for resident sellers. | Full TDS plus interest, on a transaction where you deducted nothing at all. |
| Forgetting surcharge and cess | 12.5% is the number in the headlines. The surcharge table is not. | Roughly 1.8 to 2.5 percentage points of the sale price — ₹3.7 lakh on a ₹1.5 crore flat. |
| Not checking residential status properly | The seller has an Indian passport, an Aadhaar and an Indian address, so the buyer assumes resident. | The entire NRI deduction, plus interest, plus a disallowance risk. The passport proves citizenship, not residence. |
| One Form 141 for two buyers | It seems simpler to put the whole amount on one PAN. | A mismatch between the sale deed and the TDS record, and a defective filing for both buyers. Each deductor must file separately. |
| Deducting only on the final payment | The buyer thinks TDS attaches to registration, not to payment. | Interest at 1% per month on every earlier instalment, running from the date each one was paid. |
| Deducting less because the seller "has applied" for a certificate | The seller shows the Form 128 acknowledgement and asks for a concession. | An application is not a certificate. Until the certificate is issued and in your hands, the full rate applies. |
| A company or firm using the new PAN route | The headline says "no TAN needed" and the exception is missed. | The relief is only for resident Individuals and HUFs. Every other buyer still needs a TAN. |
🔄 One genuine grey area in the transition
Suppose the tax was deducted on or before 30 September 2026 but is being deposited on or after 1 October 2026. The notification does not say which route such a case follows — the old TAN-based challan and quarterly statement, or the new Form 141 – Schedule E.
The sensible reading is that the new route applies to deductions made on or after 1 October 2026, and that a September deduction stays on the old track. But the position is not spelled out. If your transaction straddles the date, confirm the route on the portal — or with us — before you file. Filing on the wrong track and correcting it later is far more painful than asking first.
Three Worked Examples
Same rule, three price points — including the one everybody gets wrong.
Mr A, a resident individual, buys a flat in Mumbai for ₹40 lakh from Mr B, who lives in Dubai and has held the flat for nine years. Payment and registration on 20 November 2026.
Long-term, so base rate = 12.50%
Surcharge (≤ ₹50 lakh) = Nil
Cess @ 4% = 0.50%
Effective rate = 13.00%
TDS to deduct = ₹5,20,000
Paid to Mr B = ₹34,80,000
Mr A files Form 141 – Schedule E on his own PAN by 30 December 2026 and issues Form 132 to Mr B by 14 January 2027. No TAN application at any stage. Had Mr A relied on the "₹50 lakh" rule and deducted nothing, he would have been personally liable for ₹5.20 lakh plus interest.
Mrs C and her husband jointly buy a flat for ₹1.5 crore in equal shares from an NRI seller who has held it for twelve years.
Base rate (long term) = 12.50%
Surcharge @ 15% (₹1–2 cr) = 1.875% → 14.375%
Cess @ 4% = 0.575%
Effective rate = 14.95%
Total TDS = ₹22,42,500
Mrs C's share (50%) = ₹11,21,250 — her own Form 141
Husband's share (50%) = ₹11,21,250 — his own Form 141
Two buyers, two separate Form 141 filings, two PANs. Had they deducted a flat 12.5% and forgotten surcharge and cess, they would have deducted ₹18.75 lakh — a shortfall of ₹3,67,500 plus interest.
Same facts, except the NRI seller applies in Form 128 under Section 395(1) two months before registration. The property was bought in 2013 for ₹85 lakh, so the actual long-term gain is ₹65 lakh, and the tax on that gain is far below ₹22.42 lakh. The officer issues a certificate fixing the TDS on the gain instead of on the price — ₹65,00,000 × 14.95% = ₹9,71,750.
TDS with the certificate = ₹9,71,750 (14.95% of the ₹65 lakh gain)
Seller's cash freed up = ₹12,70,750, immediately rather than after filing a return
The buyers deduct the certified amount, quote the Section 395 certificate number in Schedule E, and are fully protected. This is why the certificate is worth starting six to eight weeks before the sale — it is the difference between a smooth closing and a seller who cannot fund their next purchase.
✅ The Buyer's Checklist
Print this. Work through it in order. Every item protects you, not the seller.
- Confirm the seller's residential status in writing before you agree on anything. Do not rely on a passport, an Aadhaar or an Indian address.
- Check whether you qualify for the new route — buyer must be a resident Individual or HUF, asset must be land (non-agricultural) or a building.
- Ask the seller to apply in Form 128 under Section 395(1) for a lower deduction certificate, six to eight weeks before registration. This is in both your interests.
- Work out the correct rate — 13.00%, 14.30% or 14.95% of the full sale consideration, depending on the price band. Not 1%.
- Write the TDS clause into the agreement, including who bears it and what documents the seller must provide.
- Collect PAN or TRC and TIN, overseas address, phone and e-mail from every seller before releasing money.
- Deduct on every payment — the advance, each instalment and the final payment — at payment or credit, whichever is earlier.
- File Form 141 – Schedule E on your own PAN within 30 days from the end of the month of deduction. One form per buyer.
- Save the acknowledgement number — you will need to quote it on the next instalment.
- Download Form 132 from TRACES and give it to the seller within 15 days of the Form 141 due date.
- If your deduction falls on either side of 1 October 2026, confirm which route applies before filing.
- Keep the full file for at least eight years — agreement, sale deed, TRC, certificate, challan, Form 141 acknowledgement and Form 132.
📌 Key takeaway: Notification 121/2026 removes the single most unreasonable obstacle facing an ordinary home buyer — being forced to register as a tax deductor for a once-in-a-lifetime purchase. From 1 October 2026, your PAN is enough. But the relief is procedural only. The rate is still 13% to 14.95% of the entire sale price, there is still no ₹50 lakh threshold, and the money is still recovered from you if you get it wrong. Simpler paperwork, same responsibility.
❓ Frequently Asked Questions
Do I really not need a TAN to buy property from an NRI any more?
Correct, if you are a resident individual or HUF and the deduction is made on or after 1 October 2026. You deposit and report the TDS using your own PAN in Form 141 – Schedule E. If the buyer is a company, firm, LLP or any other entity, a TAN is still required.
Is there any minimum value below which TDS does not apply on an NRI sale?
No. The ₹50 lakh threshold applies only when the seller is a resident. Where the seller is a non-resident, TDS applies on the full consideration from the first rupee — a ₹40 lakh flat or a ₹15 lakh plot is fully covered.
What is the actual TDS rate I should deduct?
For a long-term holding (more than 24 months), the base rate is 12.5% of the entire sale consideration, plus surcharge and 4% cess. That works out to 13.00% up to ₹50 lakh, 14.30% above ₹50 lakh up to ₹1 crore, and 14.95% above ₹1 crore. For a short-term holding the rate follows the seller's slab rates, and in practice buyers deduct at the maximum slab rate of 30% plus surcharge and cess, because they cannot verify the seller's slab.
Why does the ₹50 lakh figure appear in the surcharge table if there is no ₹50 lakh exemption?
They are two unrelated rules that happen to use the same number. The ₹50 lakh threshold decides whether TDS applies at all, and exists only for resident sellers. The ₹50 lakh in the surcharge table decides the rate for a non-resident seller — below it there is no surcharge, above it surcharge of 10% applies.
Is TDS deducted on the sale price or only on the seller's profit?
On the entire sale consideration, not on the gain. This has been settled since the Supreme Court's decision in Transmission Corporation of A.P. (1999). The only way to deduct on a lower figure is a lower or nil deduction certificate — the seller applies in Form 128 under Section 395(1), or the buyer under Section 395(2).
What are Form 141 and Form 132?
Form 141 is the unified challan-cum-statement under the Income-tax Rules, 2026 — it replaced Forms 26QB, 26QC, 26QD and 26QE, which now appear as Schedules A to D. The new Schedule E covers TDS on property bought from a non-resident. Form 132 is the unified TDS certificate that replaced Forms 16B, 16C, 16D and 16E, and is what you give the seller.
By when must I file Form 141 and issue Form 132?
Form 141 must be filed, along with payment of the tax, within 30 days from the end of the month in which the tax was deducted. Form 132 must be issued to the seller within 15 days from the due date of furnishing Form 141.
My spouse and I are buying jointly. Do we file one form or two?
Two. Each buyer is a separate deductor and files a separate Form 141 on their own PAN, for their own share of the consideration. The shares reported must match the shares in the sale deed.
The NRI seller does not have a PAN. Can I still buy?
Yes. Schedule E allows reporting without the seller's PAN, but you must then obtain the seller's Tax Residency Certificate number and foreign Tax Identification Number, along with full contact and overseas address details, to avoid the higher no-PAN rate. Collect these before releasing any payment.
What happens if I deduct less than I should have?
The shortfall is recovered from you, the buyer, together with interest at 1% per month for failure to deduct and 1.5% per month from deduction to payment, and you are treated as an assessee in default. Recovering the amount from the seller afterwards is a civil dispute, not a tax remedy — and the seller is usually abroad with the money.
I am buying an under-construction flat in instalments. When do I deduct?
On every payment, at the time of payment or credit, whichever is earlier — including the booking advance. File a Form 141 for each instalment, and quote the acknowledgement number of the previous Form 141 each time, as Schedule E requires.
I deducted the tax in September 2026 but am depositing it in October. Which route do I use?
The notification is silent on this. The sensible reading is that the new Form 141 – Schedule E route applies to deductions made on or after 1 October 2026, and a September deduction stays on the old TAN-based route. Because the position is not expressly stated, confirm the route on the portal or with a professional before filing.
How does the NRI seller get the money back if too much was deducted?
By filing an Indian income tax return for that year and claiming a refund of the excess, using Form 132 as proof of the tax deposited. The refund arrives months later. This is exactly why the lower deduction certificate in Form 128, obtained before the sale, is so much better than a refund afterwards.
🤝 Buying from an NRI? Let Us Handle the TDS End to End
Residential status verification, correct rate computation, lower deduction certificate in Form 128, Form 141 – Schedule E filing and Form 132 issuance — handled by a Mumbai CA firm so that the liability never comes back to you.
📞 Book a Consultation